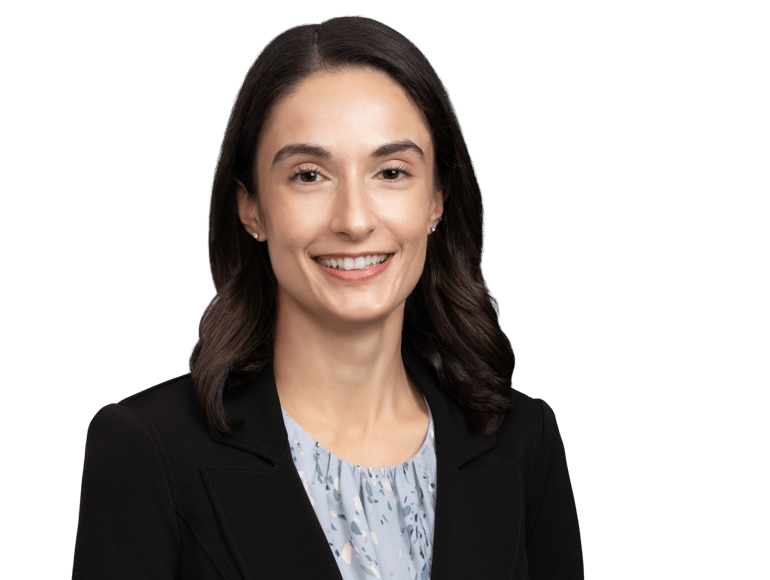
Lisa Maeyer is a member of the firm’s Casualty Department, where she focuses her practice on the defense of general liability matters including premises and automobile liability, in addition to assisting clients in matters involving insurance coverage, Personal Injury Protection (PIP) litigation, and Fraud/Special Investigation.
Lisa graduated cum laude from Gettysburg College with a B.A. in English and Writing, with honors, and a minor in Philosophy. Lisa earned her juris doctor from Villanova University Charles Widger School of Law in 2022, completing her J.D. with a litigation concentration. During law school, Lisa was a member and then executive director of the Moot Court Board.
Lisa clerked with the firm the summer of 2021 before her third year of law school, continued as a law graduate after graduating in 2022. She is admitted to practice in the state of Delaware.
Thought Leadership
Case Law Alerts
Delaware Superior Court Holds No Coverage for Opioid Litigation Under CGL Policies Despite Choice-of-Law Challenge
November 3, 2026
The Delaware Superior Court in In re Albertsons Opioid Insurance Litigation reaffirmed and expanded Delaware’s growing body of opioid insurance coverage jurisprudence, holding that commercial general liability had no duty to defend or indemnify Albertsons in more than 100 opioid-related governmental lawsuits. The Court rejected Albertsons' attempt to avoid the Delaware Supreme Court's decisions in ACE American Insurance Co. v. Rite Aid Corp. and In re CVS Opioid Insurance Litigation through a choice-of-law argument, finding no meaningful conflict between Delaware, California, and Idaho law. The decision further solidifies Delaware as a jurisdiction that narrowly construes coverage for governmental opioid claims seeking recovery of public expenditures and economic losses. Albertsons operates retail pharmacies throughout the United States and, like many pharmacy chains, has been named in numerous lawsuits arising from the opioid epidemic. Governmental entities, including states, counties, municipalities, and tribes, sought recovery for costs allegedly incurred as a result of opioid addiction, treatment, law enforcement efforts, public health programs, and other opioid-related expenditures. Albertsons tendered more than 100 underlying opioid lawsuits to its commercial general liability insurers and sought defense and indemnity coverage under more than 100 policies spanning multiple policy periods. The insurers filed declaratory judgment actions in Delaware seeking rulings that no coverage existed. Albertsons acknowledged that recent Delaware Supreme Court decisions in Rite Aid and CVS presented significant obstacles to coverage. Rather than attempting to distinguish those cases on the underlying allegations, Albertsons argued that California or Idaho law should apply because those states purportedly interpreted "damages because of bodily injury" more broadly than Delaware. The Court granted summary judgment to the insurers and denied Albertsons’ motion for partial summary judgment, first holding that there was no actual conflict between Delaware law and the laws of California or Idaho. Under Delaware's choice-of-law framework, the court need not conduct a full "most significant relationship" analysis unless competing states' laws would produce different outcomes. Here, the court found that California, Idaho, and Delaware all apply materially similar insurance-coverage principles, including: giving policy language its plain meaning; construing ambiguities in favor of the insured; interpreting coverage broadly and exclusions narrowly; and recognizing the broad nature of the duty to defend. Having determined Delaware law applied, the court found the case straightforward. The Court emphasized that Rite Aid and CVS establish that coverage for damages "because of bodily injury" requires a direct connection between the claimed damages and specific bodily injuries. Following Rite Aid and CVS, the Court held these damages were too attenuated from any specific bodily injury to trigger coverage. Consistent with CVS, the Court held that where the nature of the claims asserted falls entirely outside policy coverage, courts may determine both defense and indemnity obligations as a matter of law. Because the underlying lawsuits sought only uncovered economic losses, no duty to indemnify existed. Albertsons signals that Delaware courts are unlikely to entertain efforts by pharmacy defendants to relitigate issues already settled by Rite Aid and CVS. Unless an underlying opioid complaint seeks damages tied to specific identifiable bodily injuries or property damage, insurers will have strong grounds to deny coverage under standard commercial general liability forms.
Case Law Alerts
Delaware Superior Court Denies Summary Judgment in Snow and Ice Slip-and-Fall; No Expert Required and Causation May Be Inferred
July 20, 2026
In Mangle v. Inspirit Senior Living Dover Aid II Opco LLC, the Delaware Superior Court denied summary judgment to both a property owner and its snow-removal contractor in a slip-and-fall case arising from snowy and icy conditions in a parking lot. The plaintiff, an outpatient physical therapist working on-site, slipped while walking through a lot covered in snow and alleged that the defendants negligently failed to remediate the condition. The snow-removal contractor argued that it owed no duty because there was no evidence it performed snow and ice removal prior to the fall. The court found a genuine dispute of fact on that issue, noting that while the plaintiff testified no remediation appeared to have occurred, the contractor produced an invoice showing services performed within a timeframe that included the date of the incident. This created triable issues regarding whether the contractor performed, or should have performed, services before the fall and whether any such work was done reasonably. The court also rejected the contractor’s argument that the plaintiff’s claims failed for lack of expert testimony. Relying on Delaware precedent, the court held that expert testimony is not required where the alleged dangerous condition is within the common understanding of a lay juror. The presence of snow and ice—and whether it was reasonably addressed—was deemed the type of condition that a jury could evaluate without expert assistance. With respect to the property owner, the court declined to grant summary judgment based on the plaintiff’s inability to identify the precise cause of her fall. Although the plaintiff could not say definitively whether she slipped on snow or ice, she testified that the area was snow-covered and slippery and that ice likely existed beneath the snow. The court held that this circumstantial evidence was sufficient to permit a reasonable jury to infer that a hazardous condition caused the fall. Finally, the court rejected the defendants’ “open and obvious” argument at the summary judgment stage. Because the plaintiff alleged not only a failure to warn, but also a failure to remediate, the court found that the obviousness of the condition went to comparative fault rather than serving as a complete bar to recovery. Accordingly, the case was allowed to proceed to the jury on all issues.