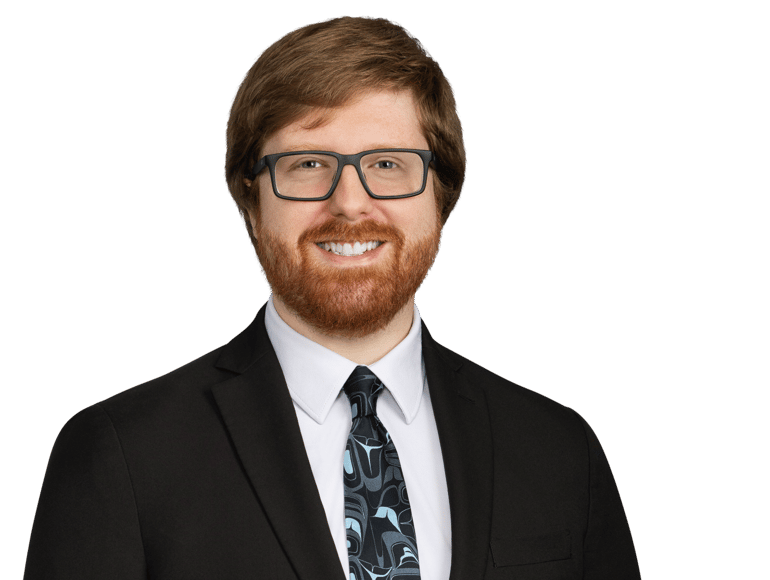
Noah Blake is an associate in our Casualty Department where he represents defendants in third-party insurance defense matters concerning negligence, automobile liability, and premises liability. He also defends insurance carriers in matters involving personal injury protection (PIP) litigation, bodily injury, and general liability.
Prior to joining Marshall Dennehey, Noah served as the Assistant Public Defender in Hillsborough County. During his time in this office, he litigated over 2,000 cases that included several trials and motions to suppress and dismiss. Notably he received a 'not guilty' verdict at trial after the jury had only deliberated for eight minutes on a case where the client was facing up to 10 years prison.
Noah earned his Bachelor of Science degree in Law Enforcement and Justice Administration from Western Illinois University. He received his juris doctor from University of Florida Levin College of Law graduating magna cum laude. While in law school, he served as Volunteer Coordinator for the Ask a Lawyer Project which helped provide free legal consultation to the homeless community in Gainesville, Florida.
When he is not working, he enjoys spending time with his family. Noah is admitted to practice in Florida.
Thought Leadership
Defense Digest
Is Your Independent Contractor Actually a “Secret” Agent?
September 30, 2026
Key Points: • A principal is vicariously liable for the negligence of an agent, but not that of an independent contractor. • If an employer’s right to control extends to the manner in which a task is completed, then an employee is an agent rather than an independent contractor. • Even though agency is generally a question for a jury to resolve, where the record is devoid of evidence to support a finding of agency, then summary judgment is appropriate. In many cases involving the alleged negligence of an independent contractor we may think the liability analysis is simple: there is no vicarious liability for an independent contractor’s negligent actions. However, this analysis does not consider whether that “independent contractor” could be considered an agent. Under Florida law, “[A] principal is vicariously liable for the negligence of an agent, but not of an independent contractor.” Del Pilar v. DHL Glob. Customer Sols. (USA), Inc., 993 So. 2d 142, 145 (Fla. 1st DCA 2008). The First District Court of Appeals’ recent ruling in the case of James v. Hernandez et al, 2026 Fla. App. LEXIS 3878 (Fla. 1st DCA May 20, 2026) provides clear guidance on the determinative test used to evaluate whether a person/entity is an independent contractor or an agent. In James, the plaintiff, Jeffrey James, was on a bicycle when he was struck by a vehicle operated by Abraham Hernandez, Jr. Hernandez owned Premier Waterproofing & Painting (“PWP”), which was a painting subcontractor for Premier Construction-Residential, LLC (“Premier”). Hernandez was traveling between Premier job sites at the time of the accident. Premier moved for summary judgment on the basis that Hernandez was an independent contractor. The plaintiff opposed the motion and asserted that Hernandez was Premier’s agent and, thus, Premier was vicariously liable for Hernandez’s negligence. At the trial court level, Premier’s motion for summary judgment was granted, but the plaintiff appealed, leading to this opinion from the 1st DCA. The 1st DCA began their analysis by considering Premier’s right to control Hernandez, and not the actual control exercised over Hernandez. They cited to Del Pilar v. DHL Glob. Customer Sols. (USA), Inc., 993 So. 2d 142, 146 (Fla. 1st DCA 2008) for the proposition that, “If the employer’s right to control the activities of an employee extends to the manner in which a task is to be performed, then the employee is not an independent contractor, but rather is an agent … .” For the purpose of analyzing Premier’s right to control, they looked at the written agreement between Premier and Hernandez. The agreement governing the relationship among Premier, Hernandez, and PWP expressly provided that Hernandez was an independent contractor. The 1st DCA specifically highlighted provisions that were consistent with Hernandez being an independent contractor such as requirements that Hernandez have his own general liability, workers’ compensation, and auto liability insurance and that Hernandez be paid in one lump sum rather than a salary or hourly wage. In addition to the agreement, the court also looked to the actual practice among the parties to determine if the relationship was one of principal or agent. The Court noted that Hernandez drove his own truck, purchased his own paint and equipment, hired and paid his own workers, and he controlled how he got to and from Premier jobsites. Despite these facts, the plaintiff tried to argue that Hernandez was Premier’s agent because Hernandez worked almost exclusively for Premier. They also argued that Premier exercised control over Hernandez’s painting methods by indicating the order in which he should paint homes in the Fletcher Oaks subdivision and which paint colors to use. Counter to these assertions, the Court recognized that Hernandez and PWP contracted with and were compensated by other companies and individuals besides Premier. Likewise, Premier contracted with other painters to paint houses in the Fletcher Oaks subdivision as well. As to the direction given to Hernandez by Premier, the court indicated that the instructions to Hernandez were essential to the work generally assigned by a build contractor to a specialty subcontractor. Considering that there were other subcontractors working within the Fletcher Oaks subdivision, Premier needed to provide instruction as to the sequence of homes to be painted and which paints to use on those homes. The court stated that these actions by Premier did not point to control over Hernandez’s methods of painting but rather control over outcomes of the job assigned. Typically, the question of whether there is an agency relationship is a question for a jury to resolve, but, in this instance, the court ultimately ruled that the plaintiff failed to present any significantly probative evidence pointing to Premier’s control over Hernandez’s painting methods to show that there was an agency relationship. As such, the 1st DCA affirmed the trial court’s ruling that Premier had no vicarious liability since Hernandez was an independent contractor. This ruling serves as a reminder not only of the agency exception to the general independent contractor rule but also the standards for ruling on a motion for summary judgment. Even though the question of agency is generally considered a question of fact for a jury, the test on summary judgment is whether there is evidence such that a reasonable jury could return a verdict for the nonmoving party. As this case demonstrates, when there is not sufficient evidence on a question of fact, then summary judgment is appropriate. Noah is an Associate in our Tampa, FL office. He can be reached at (813) 898-1817 or NEBlake@mdwcg.com.
Defense Digest
Take a Closer Look: The Precise Language of an Out-of-State Coverage Provision Leads To Varying Results
March 1, 2024
Key Points: Where the language in an insurance contract is plain and unambiguous, the courts must interpret the terms of the contract according to their plain meaning as written. Florida Statute §627.733 only requires a nonresident owner of a vehicle to maintain PIP coverage after they have been within Florida for more than 90 days of the preceding 365 days. Due to Florida’s presence requirement under Fla. Stat. §627.733 for nonresidents, an out-of-state coverage provision that only applies to unconditional out-of-state compulsory insurance laws will not provide PIP benefits in Florida. The recent ruling by the Fourth District Court of Appeal in T.I.O. Medical Intervention LLC a/a/o Mary Faison v. Liberty Mutual Fire Insurance Company, 373 So. 3d 341 (Fla. 4th DCA 2023) serves as a reminder to pay very close attention to the exact wording in insurance policy provisions. This case involved an insured that maintained a Georgia-based insurance policy but was involved in an accident in Florida. The insured was treated in Florida, and the plaintiff, a medical provider, submitted medical bills to the defendant insurer for reimbursement under Florida Personal Injury Protection (PIP) benefits. The insurer argued that the Georgia policy did not provide for Florida PIP benefits per the policy language. At the county court level, the insurer was granted summary judgment because the court found that the “clear and unambiguous” language of the Georgia policy did not provide for Florida PIP benefits. The plaintiff appealed. On appeal, the Fourth District analyzed the specific out-of-state coverage provision. Specifically, the court noted, “Where the language in an insurance contract is plain and unambiguous, a court must interpret the policy in accordance with the plain meaning so as to give effect to the policy as written.” Wash. Nat’l Ins. Corp. v. Ruderman, 117 So.3d 943, 948 (Fla. 2013). Looking first to the subject out-of-state coverage provision, the Georgia policy stated: If an auto accident to which this policy applies occurs in any state or province other than the one in which ‘your covered auto’ is principally garaged, we will interpret your policy for that accident as follows: If the state or province has: … A compulsory insurance or similar law requiring a nonresident to maintain insurance whenever the nonresident uses a vehicle in that state or province, your policy will provide at least the required minimum amounts and types of coverage. The Fourth District then looked to the presence requirement under Fla. Stat. §627.733(2) which governs PIP coverage for nonresidents: Every nonresident owner or registrant of a motor vehicle which, whether operated or not, has been physically present within this state for more than 90 days during the preceding 365 days shall thereafter maintain security as defined by subsection (3)… Fla. Stat. §627.733(2). In comparing the policy provision and the relevant Florida statute, the Fourth District concluded that the Georgia policy did not provide for Florida PIP benefits. Specifically, the court noted that the Georgia policy would only provide out-of-state coverage if the state’s compulsory insurance laws require a nonresident to have insurance “whenever” they use a vehicle. Florida law does not require a nonresident owner of a vehicle to maintain PIP coverage every time they drive, only when they have been in Florida for 90 out of the last 365 days. The plaintiffs did not present any evidence that the insured met the nonresident presence requirement under Fla. Stat. §627.733(2), but the Fourth District stated that it would make no difference to the court’s conclusion since Florida law does not “unconditionally require” nonresidents to have PIP coverage when they drive in Florida as considered by the policy. The Fourth District contrasted the Georgia policy language with out-of-state coverage provisions interpreted by the Fifth and Second District Court of Appeals. In Meyer v. Hutchinson, 861 So.2d 1185, 1186-87 (Fla. 5th DCA 2003) and Jiminez v. Faccone, 98 So.3d 621 (Fla. 2d DCA 2012), the Fifth and Second Districts analyzed an out-of-state coverage provision of an insurance policy which stated: If an insured is in another state or Canada and, as a nonresident, becomes subject to its motor vehicle compulsory insurance, financial responsibility, or similar law: This policy will be interpreted to give the coverage required by the law… The Fourth District distinguished the policy provisions interpreted by the Fifth and Second Districts from the Georgia policy provision on the basis that the former policy provision would allow coverage for nonresidents who “became subject” to Florida’s PIP statute by virtue of maintaining presence in Florida for 90 days. In comparison, the Georgia policy provision does not include the same language that would afford coverage to nonresidents who maintain presence in Florida for 90 days pursuant to Fla. Stat. §627.733(2). Therefore, the Fourth District held that the Georgia policy did not provide for Florida PIP benefits, and the lower court’s entry of summary judgment in favor of the insurer was affirmed. In light of this case, it is recommended that insurance companies review the out-of-state coverage provisions in their respective policies. As shown by this case, these provisions need to be carefully constructed so as not to afford coverage when it is not intended. They are easy to overlook, but every word is vital since courts interpret these policy provisions by their plain meaning. That is why it is important to look closely at each provision and make sure the clear meaning of the provision is what is intended. *Noah is an associate in our Tampa, Florida, office. He can be reached at (813) 898-1817 or NEBlake@mdwcg.com. Defense Digest, Vol. 30, No. 1, March 2024, is prepared by Marshall Dennehey to provide information on recent legal developments of interest to our readers. This publication is not intended to provide legal advice for a specific situation or to create an attorney-client relationship. ATTORNEY ADVERTISING pursuant to New York RPC 7.1. © 2024 Marshall Dennehey. All Rights Reserved. This article may not be reprinted without the express written permission of our firm. For reprints, contact tamontemuro@mdwcg.com.