.

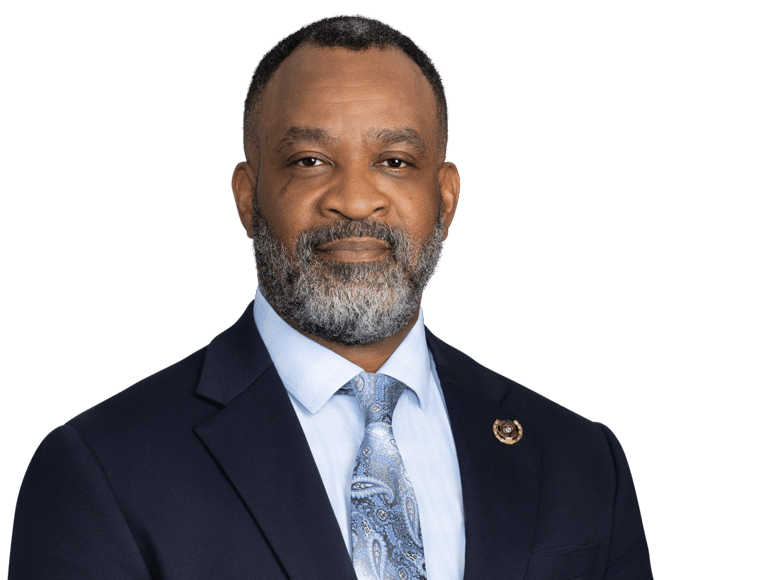
Michael G. Archibald

Portrait of Michael G. Archibald

Michael is a shareholder in the firm's Casualty Department where he represents some of the nation's largest insurance carriers and their insureds in a wide variety of product liability, premises liability, motor vehicle negligence and contract disputes. A former public defender and Marine, he brings his "hard-charging" work ethic to every engagement, whether he's assisting clients in evaluating claims made against them or defending them at trial.

With more than 20 years of experience, Michael handles all phases of litigation, from pre-suit negotiations to the courtroom, when necessary. He has successfully represented clients in routine and complex litigation involving uninsured/underinsured motorist claims, personal injury slip-and-fall matters, property damage cases, product liability matters, negligent security, and wrongful death cases.

    • University of Florida Levin College of Law (J.D., 1998)
    • Florida Agricultural and Mechanical University
      • B.S., B.C.J., magna cum laude, 1995
    • Florida, 1999
    • U.S. District Court Middle District of Florida, 2003
    • U.S. District Court Northern District of Florida, 2003
    • U.S. District Court Southern District of Florida, 2003
    • U.S. Court of Appeals 11th Circuit, 2004
    • Defense verdict in lawsuit filed against a major, nationally recognized retail chain alleging both intentional torts and negligence. Client was entitled to recover attorneys' fees and costs based on issuance of Proposal for Settlement/Offer of Judgment.
    • Favorable verdict in motor vehicle accident trial in which client admitted negligence in the operation of a motor vehicle. Verdict was favorable in that jury awarded far less than what client had previously offered plaintiff at mediation.
    • Dismissal of premises liability case after deposition of third party plaintiff. Upon careful interrogation of claimant, it was revealed during the deposition that the documents offered in support of the claim were not what they were purported to be.
    • Apartment complex owner defense: An invitee fell down a flight of concrete steps breaking bones and incurring substantial medical bills. She brought suit against the apartment complex to recover her damages. Witnesses that came to the plaintiff's aid immediately after the fall inspected the stairs and found nothing that would have caused the fall. Additionally, during her deposition testimony the plaintiff was unclear as to what she believed caused her to fall. Defendant's Motion for Summary Judgment was granted, with the defendant entitled to recover fees and costs. 
    • Retailer subrogation defense: Plaintiff insurer alleged that defective installation of a dryer caused a fire that destroyed an entire floor of an apartment complex. After paying its insured based on its contract of insurance, the insurer then filed a subrogation suit against the retail merchant. The jury returned a defense verdict  in favor of the retail merchant.  Defendant entitled to recover costs. 
    • Apartment complex owner negligent security/wrongful death defense: A 21-year-old apartment complex tenant was shot and killed during the night while in the playground area of the apartment complex. The assailant was never identified and the crime remained unsolved. He was survived by his parents and 3-year-old daughter. Lawyers for the estate made a demand in the amount of $9,000,000.00. The jury found the defendant liable for not having any security measures in place but also found the decedent to be 68 percent liable for his own death. The jury award to the estate was $333,000.00. The estate's appeal was unsuccessful. 
    • Insurance company uninsured/under-insured motorists defense: Plaintiff filed an under-insured motorists claim against his insurer based on auto accident. He had already received the policy limits from the other driver's insurance policy and sought to benefit from his UM policy. The jury agreed that the accident in question was the plaintiff's fault and rendered a defense verdict in favor of the plaintiff's insurance company.
    • Grocer defense: Plaintiff filed suit alleging that he slipped and fell in liquid that was left unattended on defendant's floor. The plaintiff had multi-level lower back surgery.  Plaintiff's key witness was a friend who was less than credible. Under cross-examination the plaintiff's and his key witness's stories diverged. The jury found in favor of the defendant. Defendant entitled to recover fees and costs.
    • Corporate defendant in rear-end auto accident: Corporate defendant fleet vehicle approached intersection wherein the traffic light was red for his lane. The fleet vehicle was second in line. The light turned green. The plaintiff  who was in the vehicle just ahead of the corporate defendant's vehicle began to go and then abruptly stopped. The fleet vehicle rear-ended the plaintiff's vehicle. In the 2 years to follow, the plaintiff had three surgeries (TMJ, knee and shoulder) all allegedly due to the rear end collision.  Defendant stipulated to liability and challenged causation. Defense verdict with defendant entitled to recover fees and costs due to offer of judgment. 
    • Retail merchant slip and fall: Plaintiff alleged that the floor was wet with liquid which caused her to slip and fall incurring an injury requiring surgery. Her key witness was her adult son who was with her when the alleged incident occurred. Despite giving deposition testimony favorable to his mother's case, at trial on cross-examination he admitted that when he inspected the floor immediately after the alleged fall, he saw nothing that would have caused her to fall. Defense verdict with defendant entitled to recover fees and costs. 
    • Retail merchant defense: Plaintiff alleged that his 2-year-old child suffered a fractured femur while inside defendant's store. The child's leg was broken due to heavy unsecured merchandise falling on his leg when he disturbed it. The jury found plaintiff/child's father 65 percent negligent for his lack of supervision of the child. Defendant entitled to recover fees based on offer of judgment. 
    • Liquor merchant slip and fall: Plaintiff patron enters liquor store out of the rain. She walked across the entire wet parking lot into the store and slipped and fell as she went to make a turn down an aisle. Defendant stipulated to the absence of a wet floor sign – jury found 65 percent negligence on plaintiff; appeal by plaintiff unsuccessful.
    • Car dealership defense/auto accident: Defendant auto dealer's employee took a newly  purchased vehicle across the street to get the tank filled for the new owner. On his way back from the gas station, the employee attempted to make a right turn on a one-way street. He did not see the plaintiff riding a bicycle on the sidewalk coming from the opposite direction of the traffic on the one-way street. 70% liability attributed to the bicycle riding plaintiff. Defendant entitled to recover fees based on offer of judgment. 
    • Retail Merchant Assault and Battery, Invasion of Privacy, Defamation: Plaintiff alleged that her privacy was invaded by defendant's employee when the employee physically assaulted her and strewn her lingerie across the parking lot of its business.  Plaintiff claimed that the employee used racial epithets against her in the course of the physical and very public assault.  Defense verdict.  Defendant entitled to fees and costs.
    • The Best Lawyers in America®, Personal Injury Litigation – Defendants (2024-2027)
    • Florida Bar Association
    • Hillsborough County Bar Association
    • National Bar Association
    • Using Crime Grids in Negligent Security Claims, Marshall Dennehey Florida Claims Symposium - The Best Defense is a Good Offense, Orlando, FL, September 17, 2014
    • “Negligent Security Claims In Florida: the “Victim-Targeted” Defense,” Defense Digest, Vol. 23, No. 1, March 2017
    • "Florida's Proposals for Settlement in Dangerous Instrumentality Cases," Defense Digest, Vol. 16, No. 2, June 2010
    • United States Marine Corps, 1987-1991

Firm Highlights

Thought Leadership

The Tolling Trap: Filing Alone Will Not Toll the Statute Without Good-Faith Service

The Eastern District of Pennsylvania recently reinforced a critical limitation on bad faith claims, holding that a timely filing alone will not preserve a cause of action absent a good-faith effort to serve the original process. The plaintiff had presented a claim for underinsured motorist benefits to his auto insurer. The insurer evaluated the claim and determined that the plaintiff’s accident-related damages did not exceed the bodily injury liability insurance limits of the at-fault driver and denied his claim. Among other claims, the plaintiff sought to present a claim for insurance bad faith under 42 Pa. C.S.A. § 8371, to which a two year statute of limitation applies. He first filed a praecipe for writ of summons before the expiration of the statute of limitation. However, the plaintiff did not attempt to serve the praecipe or writ until after the statute of limitations had expired. Additionally, the service failed as the plaintiff had mailed the original process to an incorrect address. Despite receipt of the Postal Service’s failure to deliver the original process, the plaintiff did not attempt to re-serve the writ. Two months later, the plaintiff filed a complaint and then successfully served that complaint. The insurer sought to dismiss the plaintiff’s bad faith claim as time-barred by the statute of limitations. The district court agreed. Though the plaintiff had filed a praecipe for a writ of summons prior to the expiration of the statute of limitations, the statute is only tolled if there is a good faith effort to serve that original process. In this case, the court determined that the plaintiff had failed to perform a “good faith effort to serve the original process”. Additionally, though the filing and service of a complaint can serve as alternative original process when the lawsuit is commenced by the filing of a praecipe for a writ of summons, the plaintiff filed his complaint after the statute of limitations had expired. The plaintiff’s bad faith claim was therefore determined to be barred by the statute of limitations and dismissed by the court, with prejudice. A key takeaway for the defense is not to assume that the statute of limitations has been successfully tolled by a plaintiff merely because a praecipe for a writ of summons or complaint has been filed prior to the expiration of the statute. A filed complaint or writ is only part of the equation. The defense should carefully review the docket and filings to confirm that the plaintiff also performed the requisite good faith effort to serve that original process. A thorough review of the docket may reveal that the plaintiff failed to make the good-faith service efforts necessary to toll the statute of limitations.

Thought Leadership

Commonwealth Court Reaffirms the Constitutionality of Act 111's IRE Provisions

In this case, the claimant sustained a work injury of January 6, 1994, which was acknowledged by Notice of Compensation Payable (NCP). After the claimant’s receipt of 104 weeks of temporary total disability benefits, the employer filed a Request for an Impairment Rating Examination (IRE). The IRE was performed in May 2023 and the IRE physician found that the claimant had a 5% whole person impairment, under the AMA Guides. The employer filed a Petition based on the IRE results, and the Petition was granted by the WCJ. During litigation, the claimant argued that the IRE provisions of Act 111 (Section 306(a.3) of the Act) were not applicable to her injury, since it predated June 24, 1996, the date Act 57 went into effect, and that the IRE provisions were unconstitutional. The Workers’ Compensation Judge (WCJ)) granted the Petition and the Board affirmed. On appeal to the Commonwealth Court, the claimant argued that Act 111 violated the nondelegation doctrine and that its retroactive application to the claimant’s injury was unconstitutional. The court rejected the arguments on the basis that they had already found the same arguments without merit in multiple, prior cases. The court also addressed an argument made by the claimant that Act 111 was procedurally defective under the Pennsylvania Constitution because it was only considered on two days in each House after having undergone amendments and reassignments. The court noted that the Pennsylvania Constitution requires every bill to be considered on three different days in each House. The claimant maintained that, according to the legislative history, the bill did not receive three separate days of consideration from each House when it was assigned a new bill number. The court pointed out, however, that the bill number, H.B. 1840 remained constant and was considered on three occasions by the House. Further, the court concluded that minor amendments to the bill were germane to its original subject, which was to modify the Act’s IRE process, in accordance with Protz II.

Thought Leadership

Florida Supreme Court Rules Florida Statute §627.70152 Does not Apply Retroactively

In a decision that resolves years of appellate uncertainty and confirms that insurers and insureds alike can rely on the legal framework in place when a policy is issued, the Supreme Court of Florida last week found that Florida Statute §627.70152, which involves an insured’s requirement to provide an insurer with pre-suit notice before filing a suit, cannot be applied retroactively. In Universal Property & Casualty Insurance Company v. Hughes, the Court was presented with the issue of whether the statutory pre-suit notice requirement applied retroactively and whether it would apply to a breach of contract of an insurance policy that was issued before the statute went into effect. Before the Court was an appeal from a homeowner, Ms. Hughes, who sued her insurance carrier, Universal Property & Casualty Insurance Company (Universal) for breach of contract under an insurance policy that was in effect from April 24, 2019 through April 24, 2020. During the policy period, Ms. Hughes suffered a loss and, on May 29, 2019, made a claim for water damage. The carrier investigated the loss and issued payment; Ms. Hughes disputed the payment, finding the amount insufficient for repairs. On July 1, 2021, Florida Statute §627.70152 went into effect, which required insureds to provide notice of intent to initiate litigation against the carrier prior to filing a lawsuit; if an insured filed the lawsuit without complying with §627.70152, a court must dismiss the case without prejudice. On August 4, 2021, Ms. Hughes filed her lawsuit against Universal for breach of contract. Universal moved to dismiss based on her failure to comply with §627.70152. Ms. Hughes contended the notice requirement could not be applied retroactively. The trial court disagreed and dismissed the lawsuit without prejudice, and Ms. Hughes appealed. During the appeal, the Fourth District Court of Appeal, in Cole v. Universal Property & Casualty, 363 So. 3d 1089 (Fla. 4th DCA 2023), ruled that Florida Statute §627.70152 did apply retroactively to policies issued before the effective date of §627.70152. However, the Sixth District Court agreed with Ms. Hughes and overturned the trial court’s ruling, finding the statute could not retroactively apply to policies issued prior to the statute effective date. Thereafter, the other district courts weighed in, with the Third District Court agreeing with the Fourth District Court, and the First, Second and Fifth District Courts agreeing with the Sixth District Court. In resolving the conflict amongst the district courts, the Supreme Court advised “as a general rule, ‘the statute in effect at the time an insurance contract is executed governs substantive issues arising in connection with that contract.’ Hassen v. State Farm Mut. Auto. Ins. Co., 674 So. 2d 106, 108 (Fla. 1996). The Court applied the two-step test when deciding whether a statute has retroactive application: “First, the Court must ascertain whether the Legislature intended for the statute to apply retroactively. Second, if such an intent is clearly expressed, the Court must determine whether retroactive application would violate any constitutional principles.” Menendez v. Progressive Exp. Ins. Co., 35 So. 3d 873, 877 (Fla. 2010). In analyzing the Legislature’s intent, the Court must determine whether the Legislature has manifested a clear command for retroactivity in the statutory text.  In review of the statutory text, the Court found nothing in the language of the statute to indicate that the phrase “all suits” was serving another purpose of expanding its reach to suits based on policies that both predate and postdate the enactment of the statute. Buis v. Universal Prop. & Cas. Ins. Co., 394 So. 3d 738, 741 (Fla. 2d DCA 2024). Further, the Court noted the statute has an effective date, which has long been considered to be evidence against retroactive application of a statute. The Court concluded that, on its face, no provision of §627.70152 speaks to application of the statute to insurance policies issued before the statute’s effective date and therefore, the Legislature did not clearly command retroactivity of the statute to include insurance policies issued prior to the enactment of the statute. The Court briefly reviewed Universal’s argument that the presuit notice requirement was procedural, not substantive, and therefore should be applied retroactively; however, the Court agreed with the Sixth District Court’s finding that, in its entirety, §627.70152 transformed an insured’s ability to sue an insurance company under a property insurance policy and an insurer’s obligations to respond to and pay insurance claims, thus making the requirement a substantive change. The Court thereby upheld the decision of the Sixth District and disapproved the decision of the Fourth District in Cole.