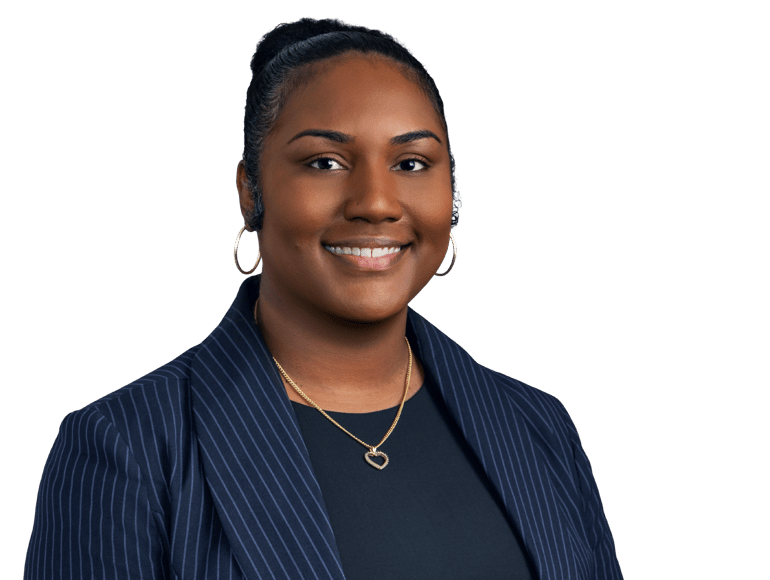
Ashley is a member of the Professional Liability Department where she focuses her practice on representing and defending insurance companies in insurance coverage disputes and first-party property litigation.
Prior to joining Marshall Dennehey, Ashley worked at an insurance defense firm where she handled personal injury protection and first party cases. She also has experience working at a consumer protection law firm providing representation to consumers against automobile manufacturers in the states of New York and Florida.
Ashley graduated from the University of Central Florida in 2010 with a Bachelor of Science degree in Legal Studies. She received her juris doctorate from Howard University School of Law.
Outside of the office, Ashley enjoys attending Miami Heat and Miami Dolphins games, traveling and spending time with her nieces and nephews.
Thought Leadership
Legal Updates for Florida Coverage and Property Litigation
Insurer Preserves Right to Appraisal by Promptly Invoking Policy Provision After Suit Filed
October 5, 2026
The appellant, People’s Trust Insurance Company (hereinafter “People’s Trust” or “Appellant”) appealed the trial court’s order denying its motion to compel appraisal. On September 8, 2022, the Appellees, Cesar Fernandez and Luz Fernandez (hereinafter “Fernandez” or “Appellees”), filed an insurance claim with People’s Trust for damages sustained to their roof and bathroom. After an inspection of the property on October 7, 2022, People’s Trust issued a coverage determination extending coverage for the roof but denying coverage for the bathroom ceiling. As a result, People’s Trust estimated the replacement cost for the repairs to be $947.51. As the amount fell below Fernandez’s $1,000 deductible, no payment was issued. Over two years later, Fernandez obtained an estimate for repairs that determined the cost of repairs to be $149,866.98. Despite standing by its initial coverage decision, People’s Trust made a $100 settlement offer in response to Fernandez’s Notice of Intent to Initiate Litigation, “without waiving its right under the insurance policy to seek legal remedies to enforce [the] insurance policy.” Fernandez filed suit against People’s Trust on April 15, 2025 for breach of contract. In response to the complaint, on May 21, 2025, People’s Trust filed its Answer and Affirmative Defenses asserting the “policy’s appraisal provision was the appropriate mechanism for resolving scope disputes between parties” as its third affirmative defense. Six days later, on May 27, 2025, People’s Trust filed a Motion to Compel Appraisal, which the trial court denied. The trial court specifically found that the actions of People’s Trust, including maintaining its coverage position and responding to the Notice of Intent to Initiate Litigation with a settlement offer was inconsistent with their right to invoke appraisal, which therefore waived its right. Here, the court addresses the potential requirement of having to invoke appraisal prior to a lawsuit being filed. The court determined that Florida Courts have consistently held that an appraisal clause may be invoked for the first time after a lawsuit has been commenced. “The operative legal standard to determine whether an insurer waived appraisal is whether the insurer actively participated in the lawsuit or engaged in conduct inconsistent with the right to appraisal.” The court specifically states that Appellant’s settlement offer in response to the Notice of Intent to Initiate Litigation alone was not a waiver of its right to appraisal, but a mere first step in resolving the matter. Appellant’s actions in this case were not inconsistent with its right to appraisal as it filed its affirmative defenses invoking appraisal, as well as filed a motion to compel appraisal promptly thereafter. Thus, the court ruled that Appellant did not waive its right to appraisal. Thus, the trial court erred in denying Appellant’s motion to compel appraisal.
Legal Updates for Coverage & Bad Faith
Coverage Determined, Judgment Paid, Bad Faith Survives: Fourth DCA’s Opinion Highlights the Distinction Between Contractual and Extra-Contractual Damages
June 24, 2026
In Healthy Food Experts, LLC v. Amguard Ins. Co., No. 4D2025-0181 (4th DCA June 10, 2026), the Fourth District Court of Appeal explained that an insurer’s payment of a judgment in a breach of contract case does not automatically eliminate a later bad faith claim seeking extra-contractual damages. The decision provides guidance on when a first-party bad faith claim may still proceed after a coverage dispute has already been resolved by a judgment. Healthy Food Experts, LLC involved a dispute related to a property damage claim submitted under a commercial insurance policy issued by the insurer following a ceiling collapse at the insured’s restaurant. The insurer denied coverage for the insured’s losses for business personal property and business income, but extended coverage for the food spoilage losses. As a result, the insured filed a breach of contract action and ultimately obtained a jury verdict. The insurer appealed the verdict and, while the appeal was pending, the insured filed a Civil Remedy Notice (CRN) seeking payment for the judgment plus interest. The insurer failed to cure the CRN within the statutory sixty-day cure period, but paid the judgement in full with accrued interest following the appeals court’s per curiam affirmance. Nevertheless, the insured filed a first party bad faith lawsuit claiming to have suffered extra-contractual damages. In response to the bad faith suit, the insurer filed a Motion to Dismiss for failure to state a cause of action, relying on Fridman v. Safeco Insurance Co. of Illinois, 185 So. 3d 1214 (Fla. 2016) stating that damages were fixed by judgment of the breach of contract suit and the insured could not recover additional damages beyond those already awarded. The insurer also argued that the judgment did not exceed the insured’s policy limits, which was a required element of a first party bad faith claim. The trial court dismissed the bad faith action based on Fridman, concluding the insured could not seek any additional damages. The insured appealed the court’s ruling to the Fourth DCA arguing the trial court’s order conflicts with Florida law and misapplies Fridman, as a contractual damage determination in the underlying suit establishes the “condition precedent to prosecute a first party bad faith action.” Cingari v. First Protective Ins. Co., 377 So. 3d 1169, 1174 (Fla. 4th DCA 2024). Further, the insured argued that the only purpose to the binding language in Fridman is to prevent the re-litigating of the same damages, which in this case are the contractual damages. The insured asserted the damages were not the “same” as they were seeking consequential damages from the insurer’s alleged bad faith. The Fourth District emphasized in its ruling that a first party bad faith claim is not ripe for litigation until there has been the following: a determination of the insurer’s liability for coverage; a determination of the extent of the insured’s contractual damages, and the required civil remedy notice is filed pursuant to §624.155(3)(a). Demase v. State Farm Fla. Ins. Co., 239 So. 3d 218, 221 (Fla. 5th DCA 2018) The court concluded that the necessary conditions were satisfied as the jury verdict determined both coverage and the extent of the insured’s contractual damages, and the insured properly filed a civil remedy notice, so the bad faith claim was ripe for litigation. The Fourth DCA further explained the insured could not seek contractual damages in its bad faith action, which was previously litigated in its breach of contract suit. However, the court determined the insured could seek “extra-contractual damages,” which were not recoverable in the insured’s breach of contract suit, which may include interest, court cost, and reasonable attorney’s fees incurred by the insured. Further, the court held excess judgment is not essential in a first party bad faith claim and the insurer’s late payment of the judgment did not preclude the insured’s bad faith action. As a result, the Fourth District Court of Appeals reversed the trial court’s final dismissal order of the bad faith action. This opinion highlights the distinction between contractual and extra-contractual damages. Moreover, this case demonstrates that a judgment does not necessarily end the dispute in a first party property claim as it is could also serve as a prerequisite of a bad faith action. The decision serves as a reminder that insurers may face bad faith exposure notwithstanding the payment of a judgment in an underlying breach of contract action.